A 1.5 Per Cent Tax on Mitumba Is a Political Decision, Not a Fiscal One
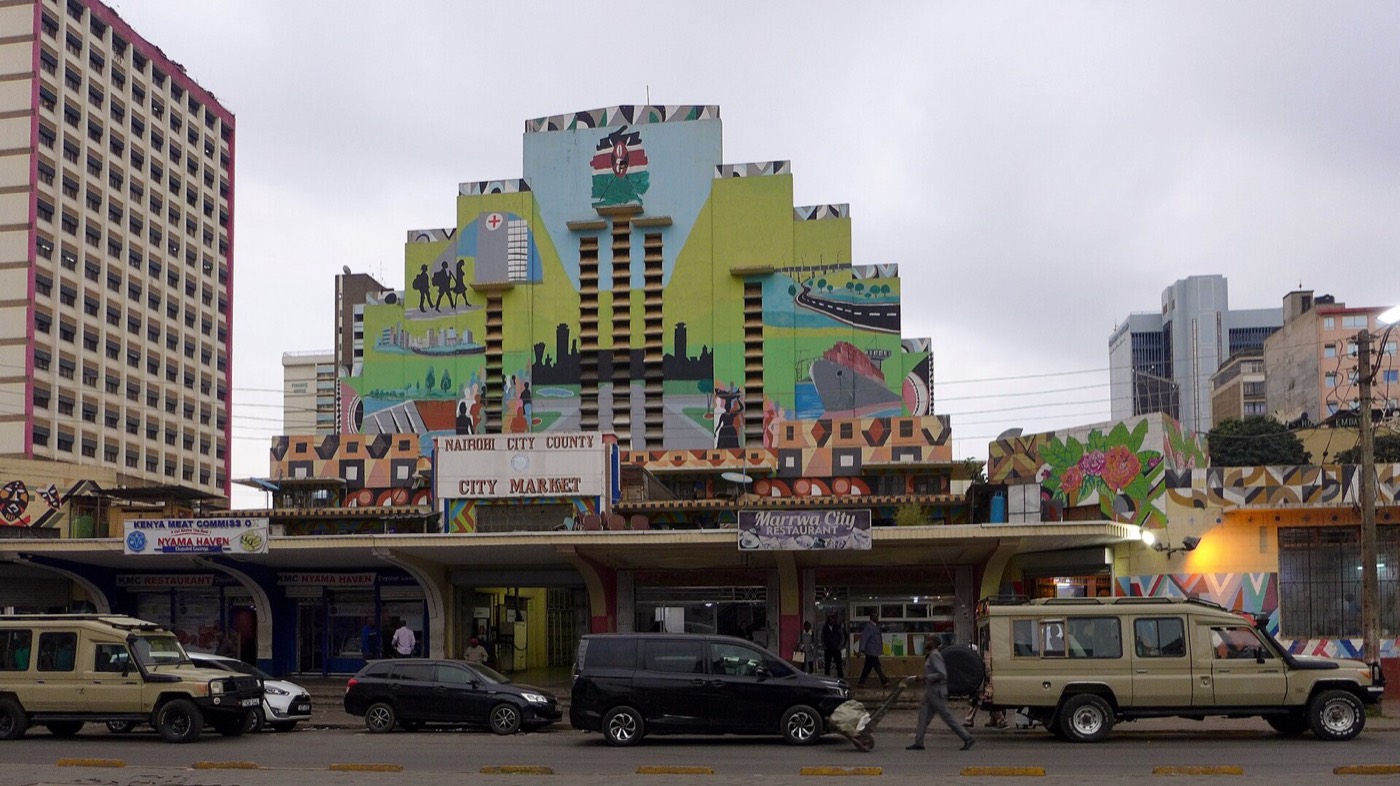
Among the measures in Kenya's Finance Bill 2026 is a levy on imported second-hand clothing — mitumba — at an implied rate of around 1.5 per cent of customs value.
As a revenue measure it is minor. As politics it is not, and the gap between those two facts is worth understanding because it repeats across Kenyan fiscal policy.
Who actually pays it
Not importers, in the end.
Mitumba moves through a chain: importer, wholesaler, bale trader, market stall, hawker. Margins thin at every step, and the people at the end of the chain are among the lowest-income traders in the country, overwhelmingly working without formal contracts or credit.
A levy on customs value is paid at the top of that chain and pushed down it. A 1.5 per cent increase in landed cost does not stay 1.5 per cent by the time it reaches a stall in Gikomba or Kongowea; it arrives as a higher bale price against a selling price the market will not bear.
Why small taxes on thin margins are politically expensive
Because the ratio that matters is not tax to price. It is tax to margin.
A trader working on a 10 per cent margin who absorbs a 1.5 per cent cost increase has lost 15 per cent of their income. That is the number they feel, and it is ten times the number in the headline.
Governments assess taxes against revenue raised. Traders assess them against what is left at the end of the day. Those two assessments diverge most sharply exactly where margins are thinnest, which is exactly where the politically loudest constituencies are.
The industrial policy argument, stated fairly
There is a genuine case on the other side, and it should not be caricatured.
Kenya has a domestic textile and apparel ambition, and cheap imported second-hand clothing is frequently cited as an obstacle to it. Several African governments have taken positions against mitumba on those grounds.
The counter-argument is that the local industry does not currently exist at the scale required to clothe the market, that taxing the substitute before the replacement exists raises prices without creating jobs, and that the jobs destroyed in the mitumba trade are real and immediate while the jobs created in textiles are hypothetical and later.
Both arguments have serious people behind them. What is not defensible is pretending the measure is only about revenue.
What this means at ward level
Market wards are their own political ecosystem, and they organise fast.
A ward containing a major market has: traders' associations, stall committees, a levy relationship with the county, and a set of grievances that are specific, current and easily verified. Those associations are already structured, already meet, and already have leaders.
For a campaign, that is the single highest-return organising target in an urban ward — and the one most often approached badly, as a place to hold a rally rather than a network to work with.
The better approach is boring: find out who the association officials are, ask what the actual complaints are, write them down with dates, and follow up on one of them. A candidate who resolved one market levy dispute has more standing in that ward than any number of visits.
Logging those complaints — with a photo, a location and a status that can be closed out — is what turns a listening exercise into a record, and it is what BallotWinners records for a ward campaign running from a phone.
Related: door-to-door at county scale.
The county levy nobody counts
A trader's tax burden does not stop at the national level. Market stalls pay county levies — daily fees, stall rent, cess on goods moving between counties — and those are set by county assemblies, which means by MCAs.
So a trader hit by a national import levy and a county market fee increase in the same year is being taxed by two governments that do not coordinate, and the one they can actually reach is the MCA.
That is worth knowing on both sides of a ward campaign. An incumbent MCA who voted for a market fee increase has a record to defend. A challenger who knows the fee schedule and can quote it has an argument nobody else in the race is making.
Frequently Asked Questions
What is the mitumba tax in Kenya's Finance Bill 2026?
A levy on imported second-hand clothing at an implied rate of around 1.5 per cent of customs value, paid at import and passed down a trading chain that ends with low-margin market traders.
Why do small taxes hit Kenyan traders so hard?
Because the relevant ratio is tax to margin, not tax to price. A trader working on a 10 per cent margin who absorbs a 1.5 per cent cost increase loses about 15 per cent of their income.