Own-Source Revenue: The Money a County Raises for Itself
Every county has two pockets. One is filled in Nairobi. The other it fills itself.
The share of national revenue is decided by legislation in each cycle and arrives on a schedule no county controls. Own-source revenue is what a county raises inside its own boundaries, and it is the only part of a county budget a county government fully owns.
What a county is allowed to charge
The Constitution is narrow about taxes and wide about charges.
Article 209 lets a county impose property rates, entertainment taxes, and any other tax authorised by an Act of Parliament. That is the tax list. It is short, and a county cannot add to it on its own.
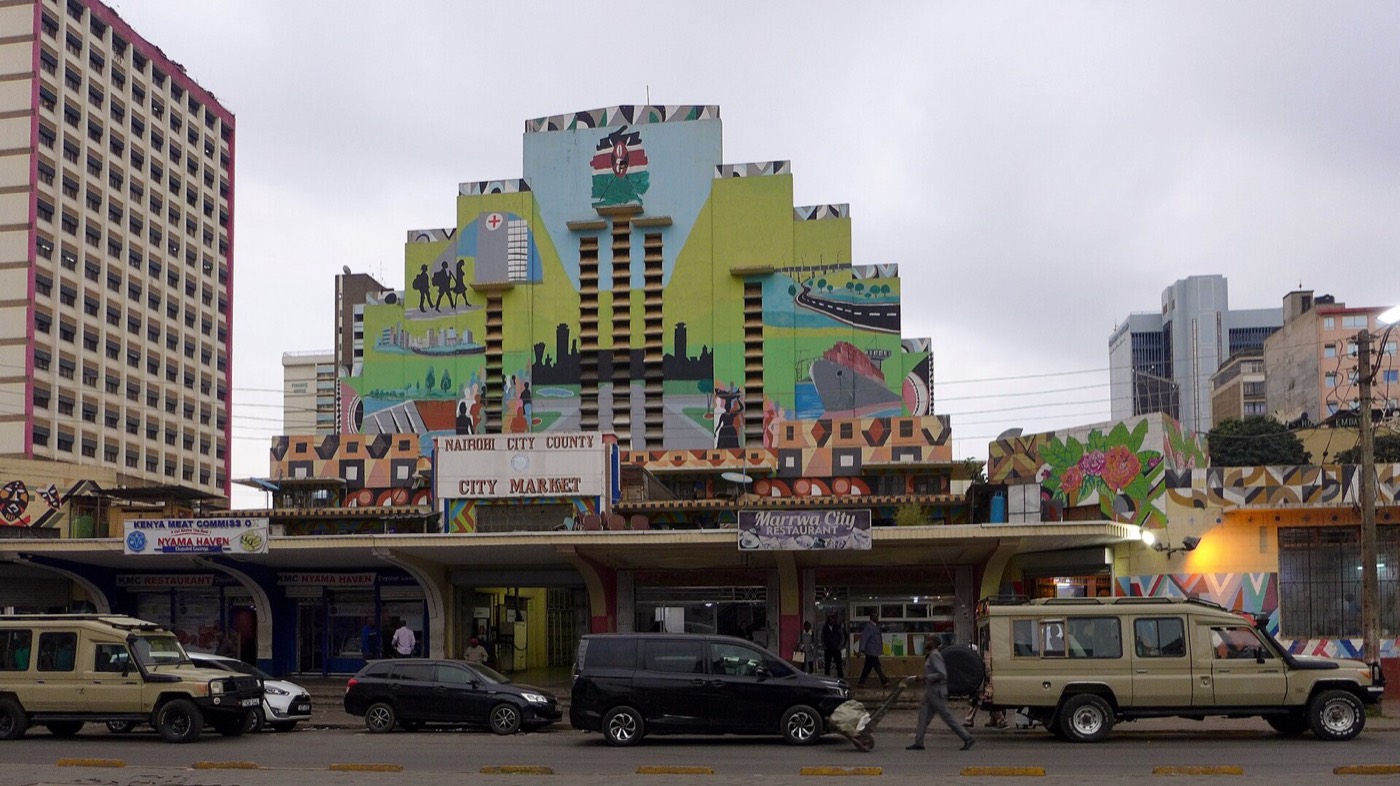
Counties may also impose charges for the services they provide, and that is where most of the money actually comes from: single business permits, market stall fees, parking, cess on produce moving through the county, building plan approval and inspection fees, outdoor advertising and signage, liquor licensing, public health inspection, hospital and clinic charges, and rent from county property.
There is a constitutional limit over all of it. Revenue-raising powers must not be exercised in a way that prejudices national economic policies, economic activities across county boundaries, or the national mobility of goods, services, capital or labour. That clause is why roadblock-style charges on goods in transit keep being challenged.
How the rates are set, and when you can object
Through a county finance act, every year.
The county proposes its fees and charges, the assembly considers the bill, public participation is required, and the assembly passes it. Once it is law, that schedule of fees is what a county officer is entitled to collect. Anything charged outside it is not a fee.
This is the single most useful document for a trader, a landlord, a matatu owner or a market vendor, and hardly anyone reads it. It is also the easiest place to be heard, because the people affected are specific and their objections are concrete. The participation rules cover how to submit an objection that gets recorded.
Where the money goes once it is collected
Into the County Revenue Fund, and not into a department.
All money raised or received by or on behalf of a county government is paid into that fund. Withdrawals from it require the approval of the Controller of Budget, against the approved budget. That is what stops revenue being spent by whoever happened to collect it.
Which is why a receipt matters. Money collected without a receipt has no route into the fund, and a payment made without one is a payment the county has no record of receiving. Automated collection, cashless payment and printed receipts exist for that reason rather than for convenience.
The Auditor-General then audits collections alongside expenditure. Own-source revenue queries are a standard feature of county audit reports: revenue collected but not banked, revenue not supported by records, targets set without a stated basis. The guide to every public fund maps who audits what.
Why the target matters as much as the collection
A county budget is built on a revenue assumption.
If a county budgets on own-source revenue it does not collect, the gap has to come out of something: pending bills, stalled projects, or a supplementary budget that cuts development. That is the mechanism behind a great many unfinished county projects, and it is visible in the documents long before it is visible on the ground.
So the question is never only how much was collected. It is how much was projected, how much came in, and what happened to the programmes that were funded on the difference. All three figures sit in county documents, and the budget process explains which document holds each one.
What to check in your own county
Start with the current county finance act.
Find the fee you or your business actually pays and check it against the schedule. Then ask the county treasury for the own-source revenue projection in the current budget and the actual collection reported for the last completed financial year. Then read the Auditor-General's revenue findings for your county.
Three documents, all public, and between them they answer more about a county's competence than any campaign speech before 10 August 2027 will. Take them to your MCA with the ten budget questions and see how far the answers go.
Frequently Asked Questions
What taxes can a county government charge in Kenya?
Article 209 of the Constitution limits counties to property rates, entertainment taxes and any other tax specifically authorised by an Act of Parliament. Separately, counties may charge for the services they provide, which covers permits, market fees, parking, inspections and similar items. Those charges are set out in the county finance act passed each year by the county assembly.
Where does county revenue go after it is collected?
Into the County Revenue Fund. All money raised or received by or on behalf of a county government is paid into that fund, and withdrawals require the approval of the Controller of Budget against the approved budget. That is why a receipt matters: revenue collected without one has no documented route into the fund and no trace in the accounts the Auditor-General later examines.